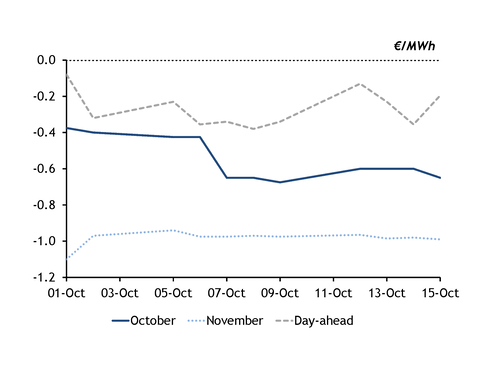
The Dutch gas balance is likely to loosen for the remainder of the month, as state-owned EBN has filled the Norg storage site and high LNG deliveries may leave ample supply available. But differentials need to widen to encourage stronger eastbound flows.
EBN is set to completely fill Norg on 16 October, with the site currently holding 59.2TWh — 99.7pc of capacity — GIE transparency data show. EBN net injected briskly into the site this summer, and net injections averaged 328 GWh/d on 1-15 October. If this pace is sustained, the site could be full by the end of today's gas day.
EBN can inject into Grijpskerk to meet the remainder of its 80TWh storage obligation, but Grijpskerk injections are restricted to 154 GWh/d, so the pace may be slower over the rest of the month. Net injections into Grijpskerk averaged 121 GWh/d on 1-15 October, and the site held 12.6TWh — 52.8pc full — this morning. EBN must inject an additional 2.4TWh into the site to reach its mandated 15TWh.
And EBN cannot direct extra volumes into Bergermeer, as the site is under maintenance and cannot receive injections until 31 October. EBN could hit its storage mandate around 4 November if injections into Grijpskerk continue at the current rate, but this depends on the volume already inside Bergermeer that was injected by EBN.
Slower injections over the second half of October could loosen the Dutch gas balance, leaving ample supply for export. This would contrast with the tight balance during summer, when slower LNG deliveries coincided with strong injection demand.
Sendout from the country's LNG terminals averaged 886 GWh/d on 1-15 October, peaking at a record 918 GWh on 15 October, and up from 766 GWh/d a year earlier. If sendout remains at the 1-15 October pace for the rest of October, it would be the highest for any month on record.
At the same time, above-average minimum temperatures in Amsterdam kept demand muted at 566 GWh/d over the first half of October, well below 770 GWh/d a year earlier. Colder weather may bolster heating-related demand on 16-31 October. Minimum temperatures are forecast to average 7.4°C on 16-31 October, down from 10.3°C the previous fortnight.
Flow east?
A loose Dutch balance might weigh on the TTF relative to THE, incentivising quicker Dutch-German flows.
Dutch exports to Germany have slowed this year, as storage obligations meant more supply was retained in the domestic grid for injections. This supported the TTF price relative to THE, significantly narrowing TTF-THE differentials for summer delivery and curbing flows through the TTF-THE virtual interconnector.
Net Dutch flows to Germany averaged 275 GWh/d on 1-15 October, down from 406 GWh/d a year earlier.
Net Dutch exports this summer averaged 383 GWh/d, as the everyday TTF-THE differential averaged a narrow -€0.261/MWh. This was down from 488 GWh/d a year earlier, when the differential was a wider -€0.609/MWh.
The TTF-THE day ahead basis-market closed at -€0.195/MWh on Thursday's close, suggesting minimal Dutch exports. But the TTF-THE weekend differential was -€0.445/MWh by midday Friday, which could incentivise quicker flows over that period. And the TTF-THE balance-of-month basis market closed at a wider -€0.65/MWh on Thursday evening, out from -€0.375/MWh on 1 October, which could indicate quicker flows over the remainder of the month.
If TTF-THE prompt differentials continue to widen over the rest of this month, shippers could be encouraged to bolster exports to Germany, especially since Germany is not close to its stock target.
Germany depended on limited Belgian supply, intermittently curtailed Norwegian flows and LNG imports that were stymied by poor margins to support summer injections. And supply conditions have not improved, with no LNG currently bound for Germany. But brisk Dutch flows to Germany over the second half of the month could lift injections.
Germany's stocks were at 60.5pc of capacity as of Friday morning, holding below the European average of 74pc. And without any meaningful government intervention to accelerate net injections before 1 November, the country is on track to miss its 70pc fill target by 1 November, even if Dutch receipts increase over the second half of this month.