

European naphtha prices drop behind oil product pack
The European naphtha market has been weak this summer, even during extreme spikes in other oil product markets, as naphtha demand from Europe’s petrochemical industry is in a long-term slump.
Author
European naphtha prices have lagged other oil products as weak petrochemical demand, high stocks and Rhine transport constraints weighed on the market. Stronger gasoline blending and exports to Asia and the US helped ease oversupply, but increasing competition from cheaper LPG, particularly US propane, could limit a recovery in naphtha demand this autumn.
The US-Iran and Russia-Ukraine wars have driven prices for European oil products — like diesel and jet fuel — to the highest on Argus records this year. Naphtha, a petrochemical feedstock and gasoline blendstock, looked set for a colossal price spike because it is usually the largest product export stream from the strait of Hormuz, behind liquefied petroleum gas (LPG).
But Europe’s petrochemical industry has struggled this year with subdued margins, even as other oil product margins have risen to exceptionally high levels. Petrochemical cracker utilisation rates were at just 65-70pc at times during the summer, according to market participants.
As the petrochemical industry kept its foot on the brake, independent stocks of naphtha at the Amsterdam-Rotterdam-Antwerp (ARA) hub grew by around 50pc between July and August, according to consulting firm Insights Global (see Chart 1).
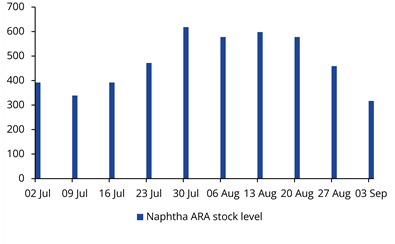
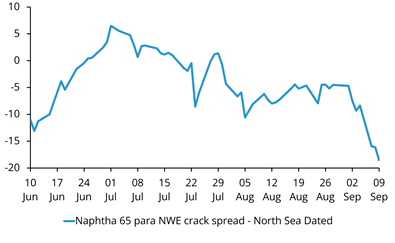
Chart 1 & 2: Independntly held naphtha stocks via consultancy Insights Global & European napthha cracks
Low Rhine water levels add to European naphtha pressure
Navigation restrictions disrupted barge movements between ARA and inland Germany, pushing up freight costs and limiting feedstock deliveries to petrochemical producers, according to market participants.
Several petrochemical facilities, including those at Wesseling and Ludwigshafen, were affected by the disruption. Alternative delivery methods helped mitigate the impact, but were not able to fully replace lost barge capacity.
The logistical constraints reduced demand for naphtha at a time when petrochemical consumption was already weak, reinforcing concerns about oversupply in the region.
While demand from the petrochemical sector remained weak, stronger gasoline markets provided support for naphtha.
European gasoline fundamentals were supported by robust export demand from destinations including Brazil, west Africa and Turkey, according to market participants. Stronger gasoline values improved blending economics, creating an attractive outlet for naphtha.
The gasoline-naphtha spread widened during August, encouraging greater use of naphtha in gasoline blending and helping to absorb part of the regional surplus (see chart 3).
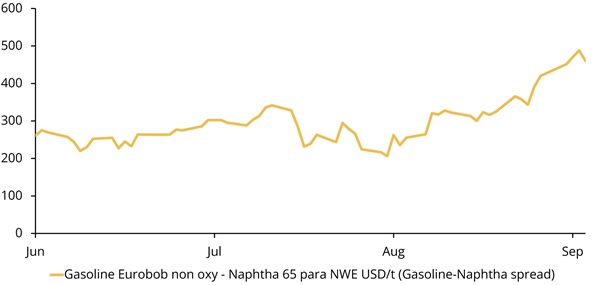
Chart 3: European gasoline-naphtha spread
Export markets also began to provide some relief
Stronger demand from Asia supported Mediterranean naphtha exports during August, according to market participants and ship-tracking platform Vortexa. Asian demand grew after seasonal maintenance shutdowns and earlier production outages ended at several petrochemical facilities.
US demand also increased as European naphtha prices became more competitive. Cargoes were used in both gasoline blending and the processing of heavier crude grades.
Improved export opportunities helped reduce oversupply in Europe by drawing surplus naphtha away from the domestic market. Combined with stronger gasoline blending demand, this led to more upbeat market sentiment towards the end of August.
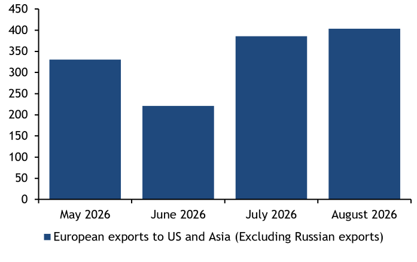
Chart 4: European naphtha exports to Asia and the US
Competition from relatively low-cost LPG, an alternative petrochemical feedstock, is now creating fresh pressure for naphtha prices.
Northwest Europe has attracted increasing volumes of US propane in recent months, according to Kpler (see Chart 5). At the same time, propane has become significantly cheaper than naphtha, according to market participants. For petrochemical producers able to switch between feedstocks, cheaper LPG can be a more attractive option than naphtha, potentially limiting any recovery in naphtha demand during the autumn.
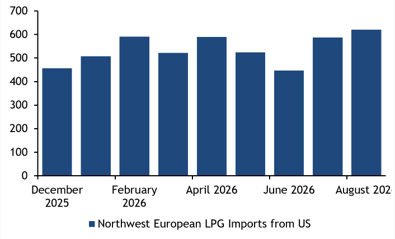
Chart 5: Northwest Europe LPG imports from US
The insights come from Argus European Products, the leading source for prices and analysis of key petroleum products, including the benchmark for northwest European gasoline. See details here.
European naphtha prices have lagged other oil products as weak petrochemical demand, high stocks and Rhine transport constraints weighed on the market. Stronger gasoline blending and exports to Asia and the US helped ease oversupply, but increasing competition from cheaper LPG, particularly US propane, could limit a recovery in naphtha demand this autumn.


