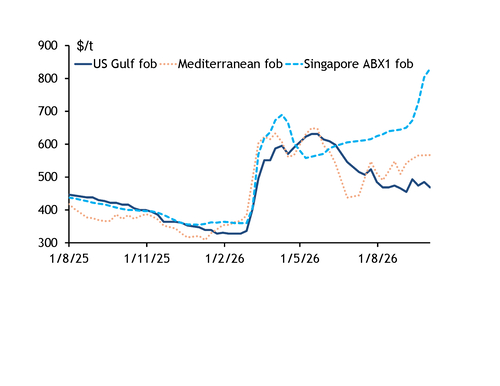
A price rally in Asia bitumen, supported by particularly tight supply from Singapore and South Korea, is drawing in much cheaper arbitrage cargoes from both Europe and the US.
Price spreads between Asia and the rest of the world are now at multi-year highs, while tight supply in export hubs Singapore and South Korea looks set to continue through until at least the end of October, while Mideast Gulf supply remains heavily restricted by US sanctions and shipping limitations through the strait of Hormuz.
Singapore bitumen prices had a premium of $263/t over Mediterranean cargoes and $361/t over US Gulf exports as at 2 October (see chart).
Disruptions to crude supply via the strait of Hormuz have limited suitable crude feedstock for refiners in Asia, while a major Singapore refinery will further reduce supply this month as a result of maintenance.
In the Mediterranean differentials to high-sulphur fuel oil (HSFO) have been falling through September as more supply became available, particularly from Greek, Italian and Spanish export points, while regional demand has been weaker on funding issues and some pushback on high outright prices after US-Iran tensions increased. Greek premiums to HSFO were around $30/t in August, but now Argus assessments stand at $7.50/t above HSFO. September and October would usually be among the busiest months for the European export market, before a winter slowdown when road works are reduced, but this year poorer funding and high outright prices have slowed demand.
US Gulf prices are now particularly attractive and with seasonal paving and roofing demand starting to fall there — and with supplies ample — prices look set to remain weak. Strong margins have also led many US refiners to run at high rates and produce more bitumen, along with higher value products.
Earlier this year the arbitrage to Asia also briefly opened, but now with the price premium in Asia higher, more cargoes are expected into the region through until at least November, according to traders.
Import demand from Oceania and southeast Asian markets is expected to remain firm in the coming months because the peak road-paving season is now under way. Importers are actively seeking supply alternatives as traditional producers Singapore and Thailand have limited output.
Argus assessed the fob Singapore ABX 1 at $830/t on 2 October, up by $26.50/t from the previous week. Singapore bitumen prices have climbed consistently since early September, thanks to firmer import demand from southeast Asian importers, particularly in Vietnam, as well as supply tightness.
The fob South Korea ABX 2 assessment stood at $815/t on 2 October, up by $32/t on the week. ABX 2 prices have been climbing steadily since mid-August, owing to firmer buying interest from key consumer east China, where higher domestic offers and tight domestic output have supported the market.
Movements include the 17,779 deadweight tonne (dwt) White Allegra heading from Greece, having loaded 11 September, and set to arrive at Singapore on 8 October, according to vessel tracking data.
The 36,771 dwt Asphalt Synergy loaded in the US Gulf in mid-September and is expected to Tauranga, New Zealand on 15 October.
The 36,754dwt White Pearl loaded a multi-port cargo from Tarragona, Spain, on 7 August, and made its final stop at Napier, New Zealand, on 6 October.
The 13,265dwt Jin Zhou Wan is also expected to move to Oceania and loaded in the US Gulf on 26 September, while the 12,972 dwt Da Hua Shan arrived at Geelong in Australia on 3 October having loaded in Louisiana, US, in mid-August.