

A divided outlook for European base oils
Explore how disrupted trade, refinery outages and uneven inventories are driving contrasting price trends across Europe’s base oil groups.
Author
At a glance
- Group I and II prices declined amid weak seasonal demand.
- Supply disruptions failed to reverse the downward trend in Group I markets.
- Buyers remained well stocked after purchasing during earlier supply concerns.
- Group III supply stayed tight due to import disruptions and refinery maintenance.
- Record-high Group III prices persisted as buyers competed for limited volumes.
European base oils: Disruptions fail to shift market direction
Demand for European Group I base oils remained lacklustre throughout the summer and into September despite significant disruptions to feedstock supply and refinery operations. At the same time, Group III prices continued to face upward pressure as global supply constraints tightened availability and kept buyers competing for limited volumes.
Recent attacks on Saudi Arabia's East-West crude pipeline and an increase in Group III cargo movements to Europe have done little to alter established pricing trends. While Group I and Group II prices extended their decline amid weak demand, Group III values continued to climb on persistent supply shortages.
Summer slowdown compounded by supply disruptions
Group I and Group II spot prices came under pressure in the summer as seasonal demand weakened. But unlike a typical summer lull, buying interest was further dampened by the exceptionally high prices seen earlier in the year following the start of the US-Iran conflict and widespread refinery maintenance.
Although Europe accounts for more than 60pc of global Group I nameplate capacity, a combination of planned and unplanned refinery shutdowns significantly tightened availability. At the same time, weak diesel imports encouraged refiners to maximise fuel production rather than base oil output, adding further pressure to supply balances.
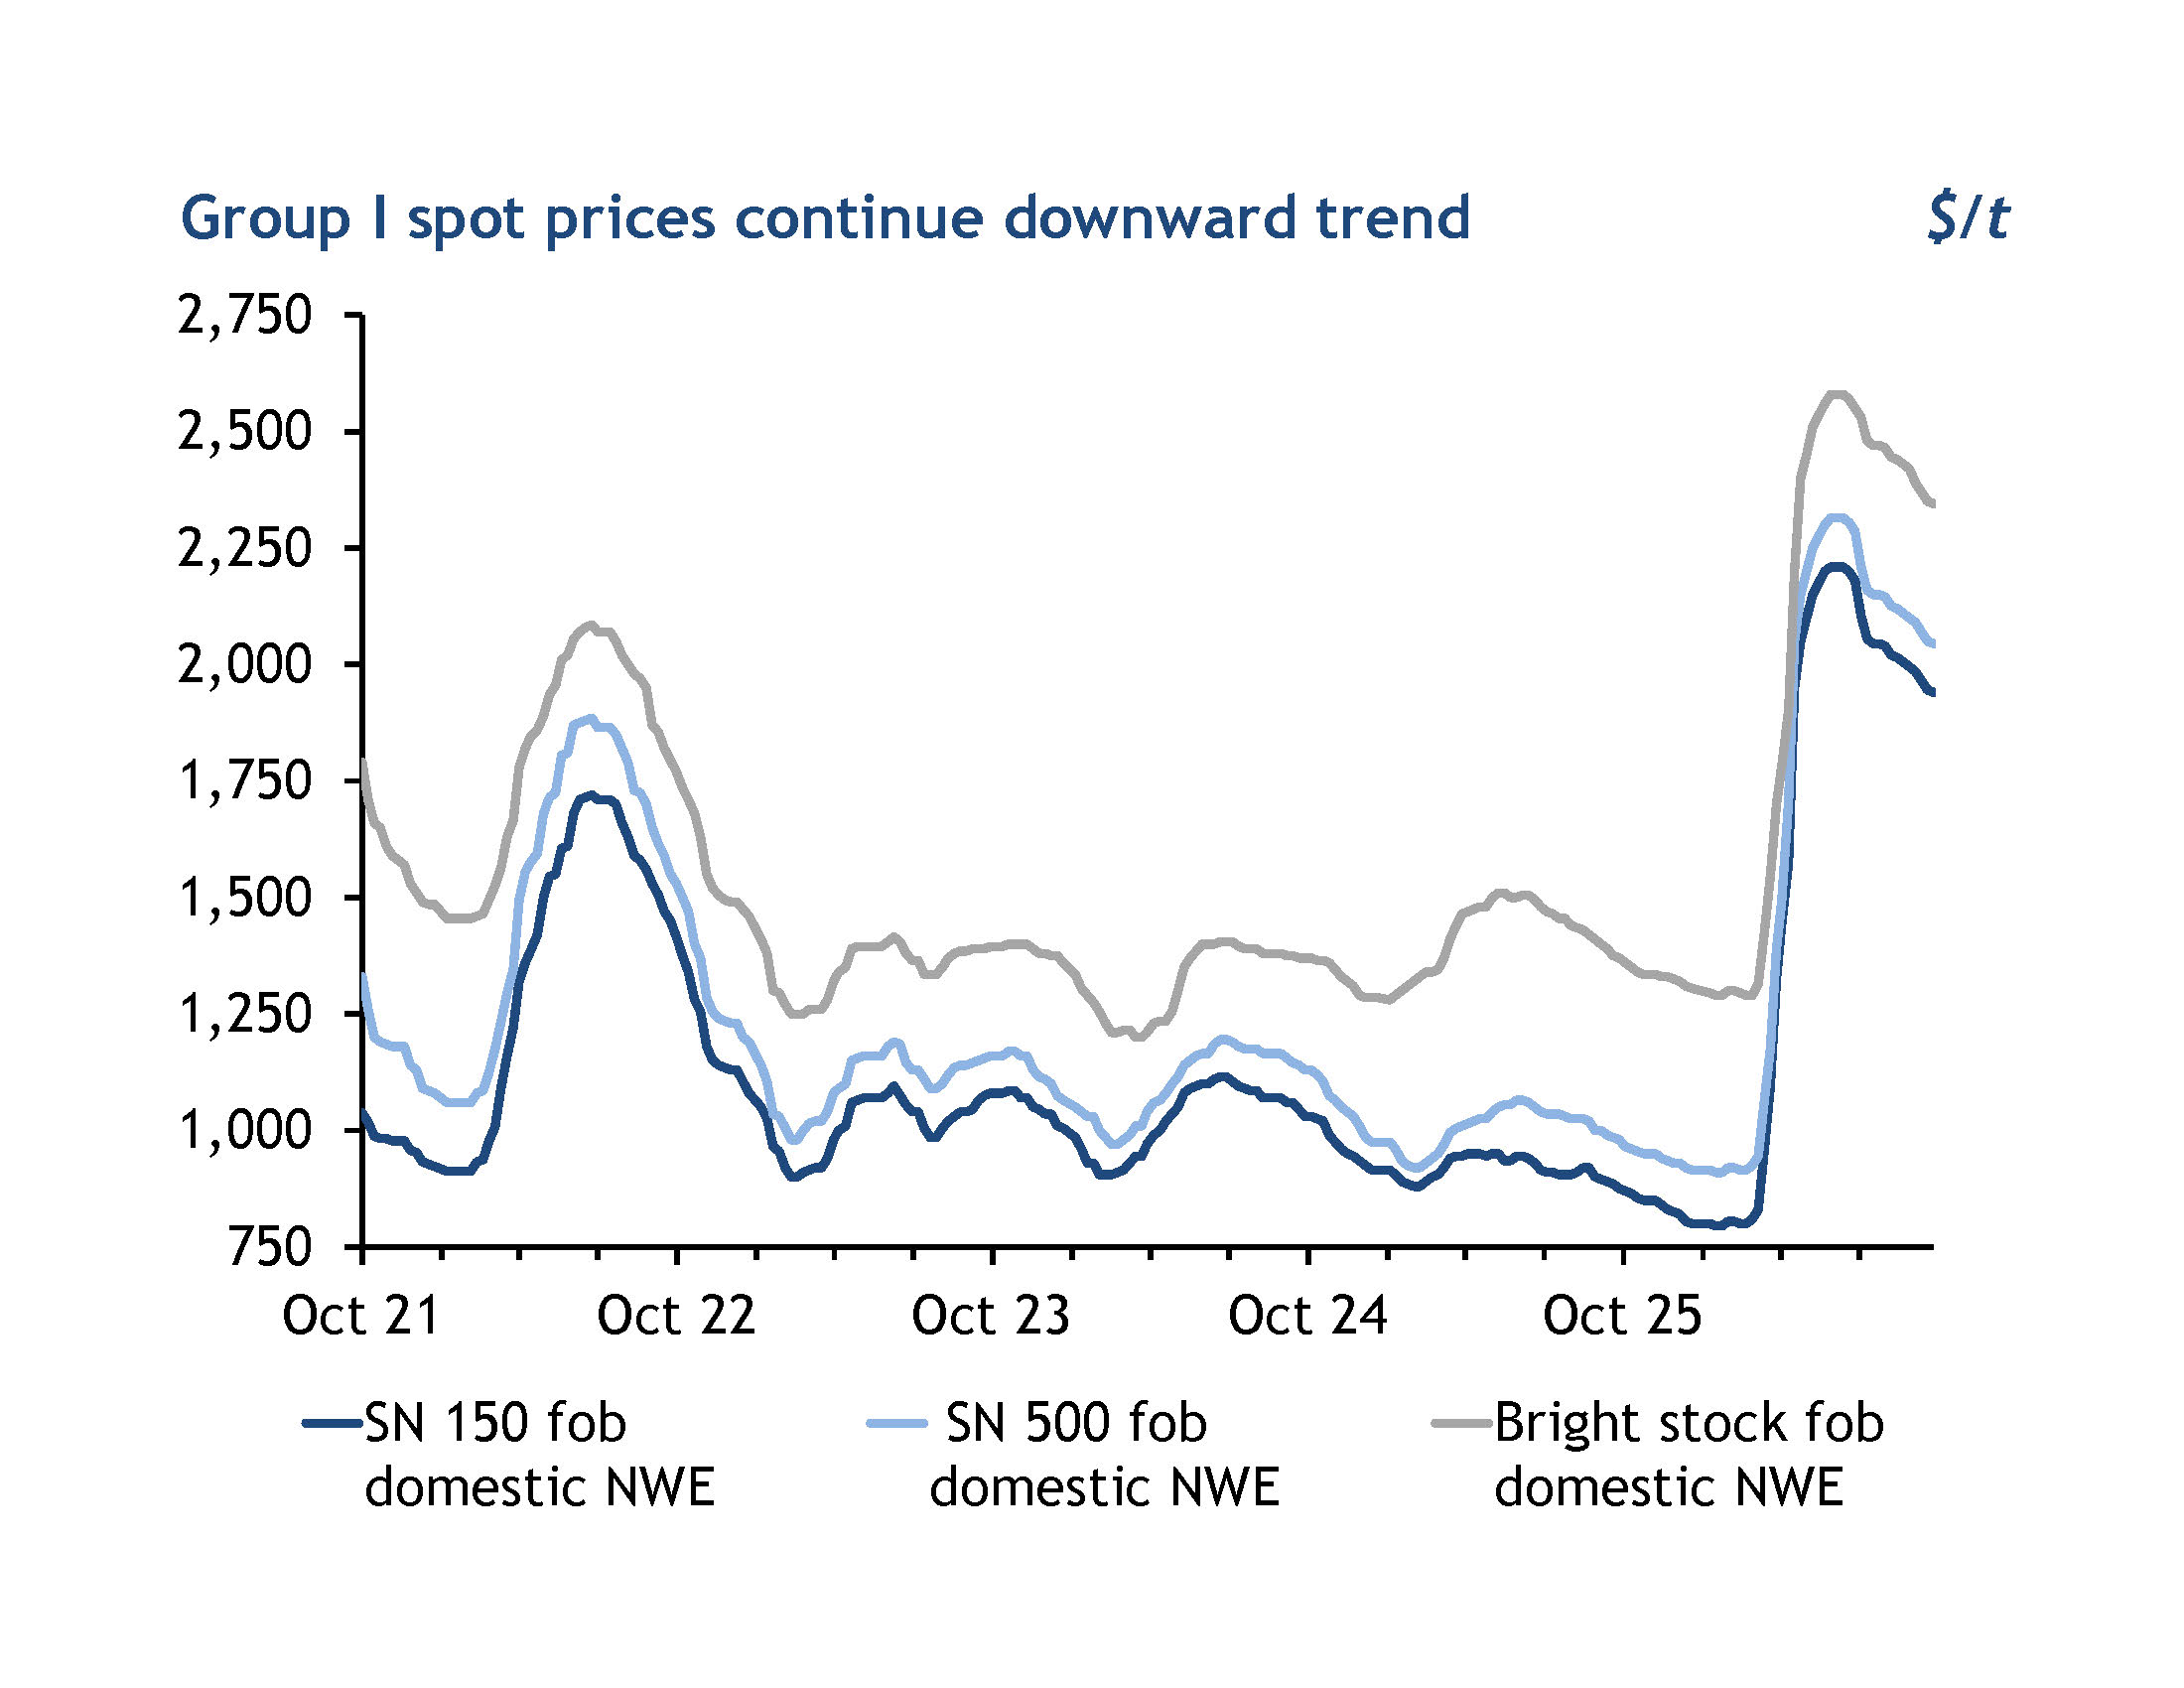
As maintenance programmes concluded and production recovered, buyers became increasingly reluctant to purchase at historically elevated prices. Many blenders had already secured volumes during the height of the supply concerns and entered the summer with ample inventories purchased at premium prices.
As a result, prices fell throughout the third quarter despite limited spot market activity. Demand also failed to recover in September, a period that typically marks the return of replenishment buying following the summer holidays.
Latest supply disruptions yet to revive demand
The 10 September attack on Saudi state-controlled Aramco's East-West pipeline reduced crude feedstock availability in Europe for October, forcing several refiners to seek alternatives. But despite the tighter feedstock conditions and ongoing prioritisation of strategic fuels, the impact on the base oils market has been limited.
Group I prices continued to move lower, although values remain historically high. With blenders still carrying significant inventories and demand yet to recover, the latest disruption has failed to reverse the prevailing market trend.
Group III market remains exceptionally tight
The outlook has been markedly different for Group III. Europe remains heavily dependent on imports, with Middle Eastern producers typically accounting for as much as 60pc of imports. Those flows have been severely disrupted since the de facto closure of the strait of Hormuz following the escalation of the US-Iran conflict earlier in the year.
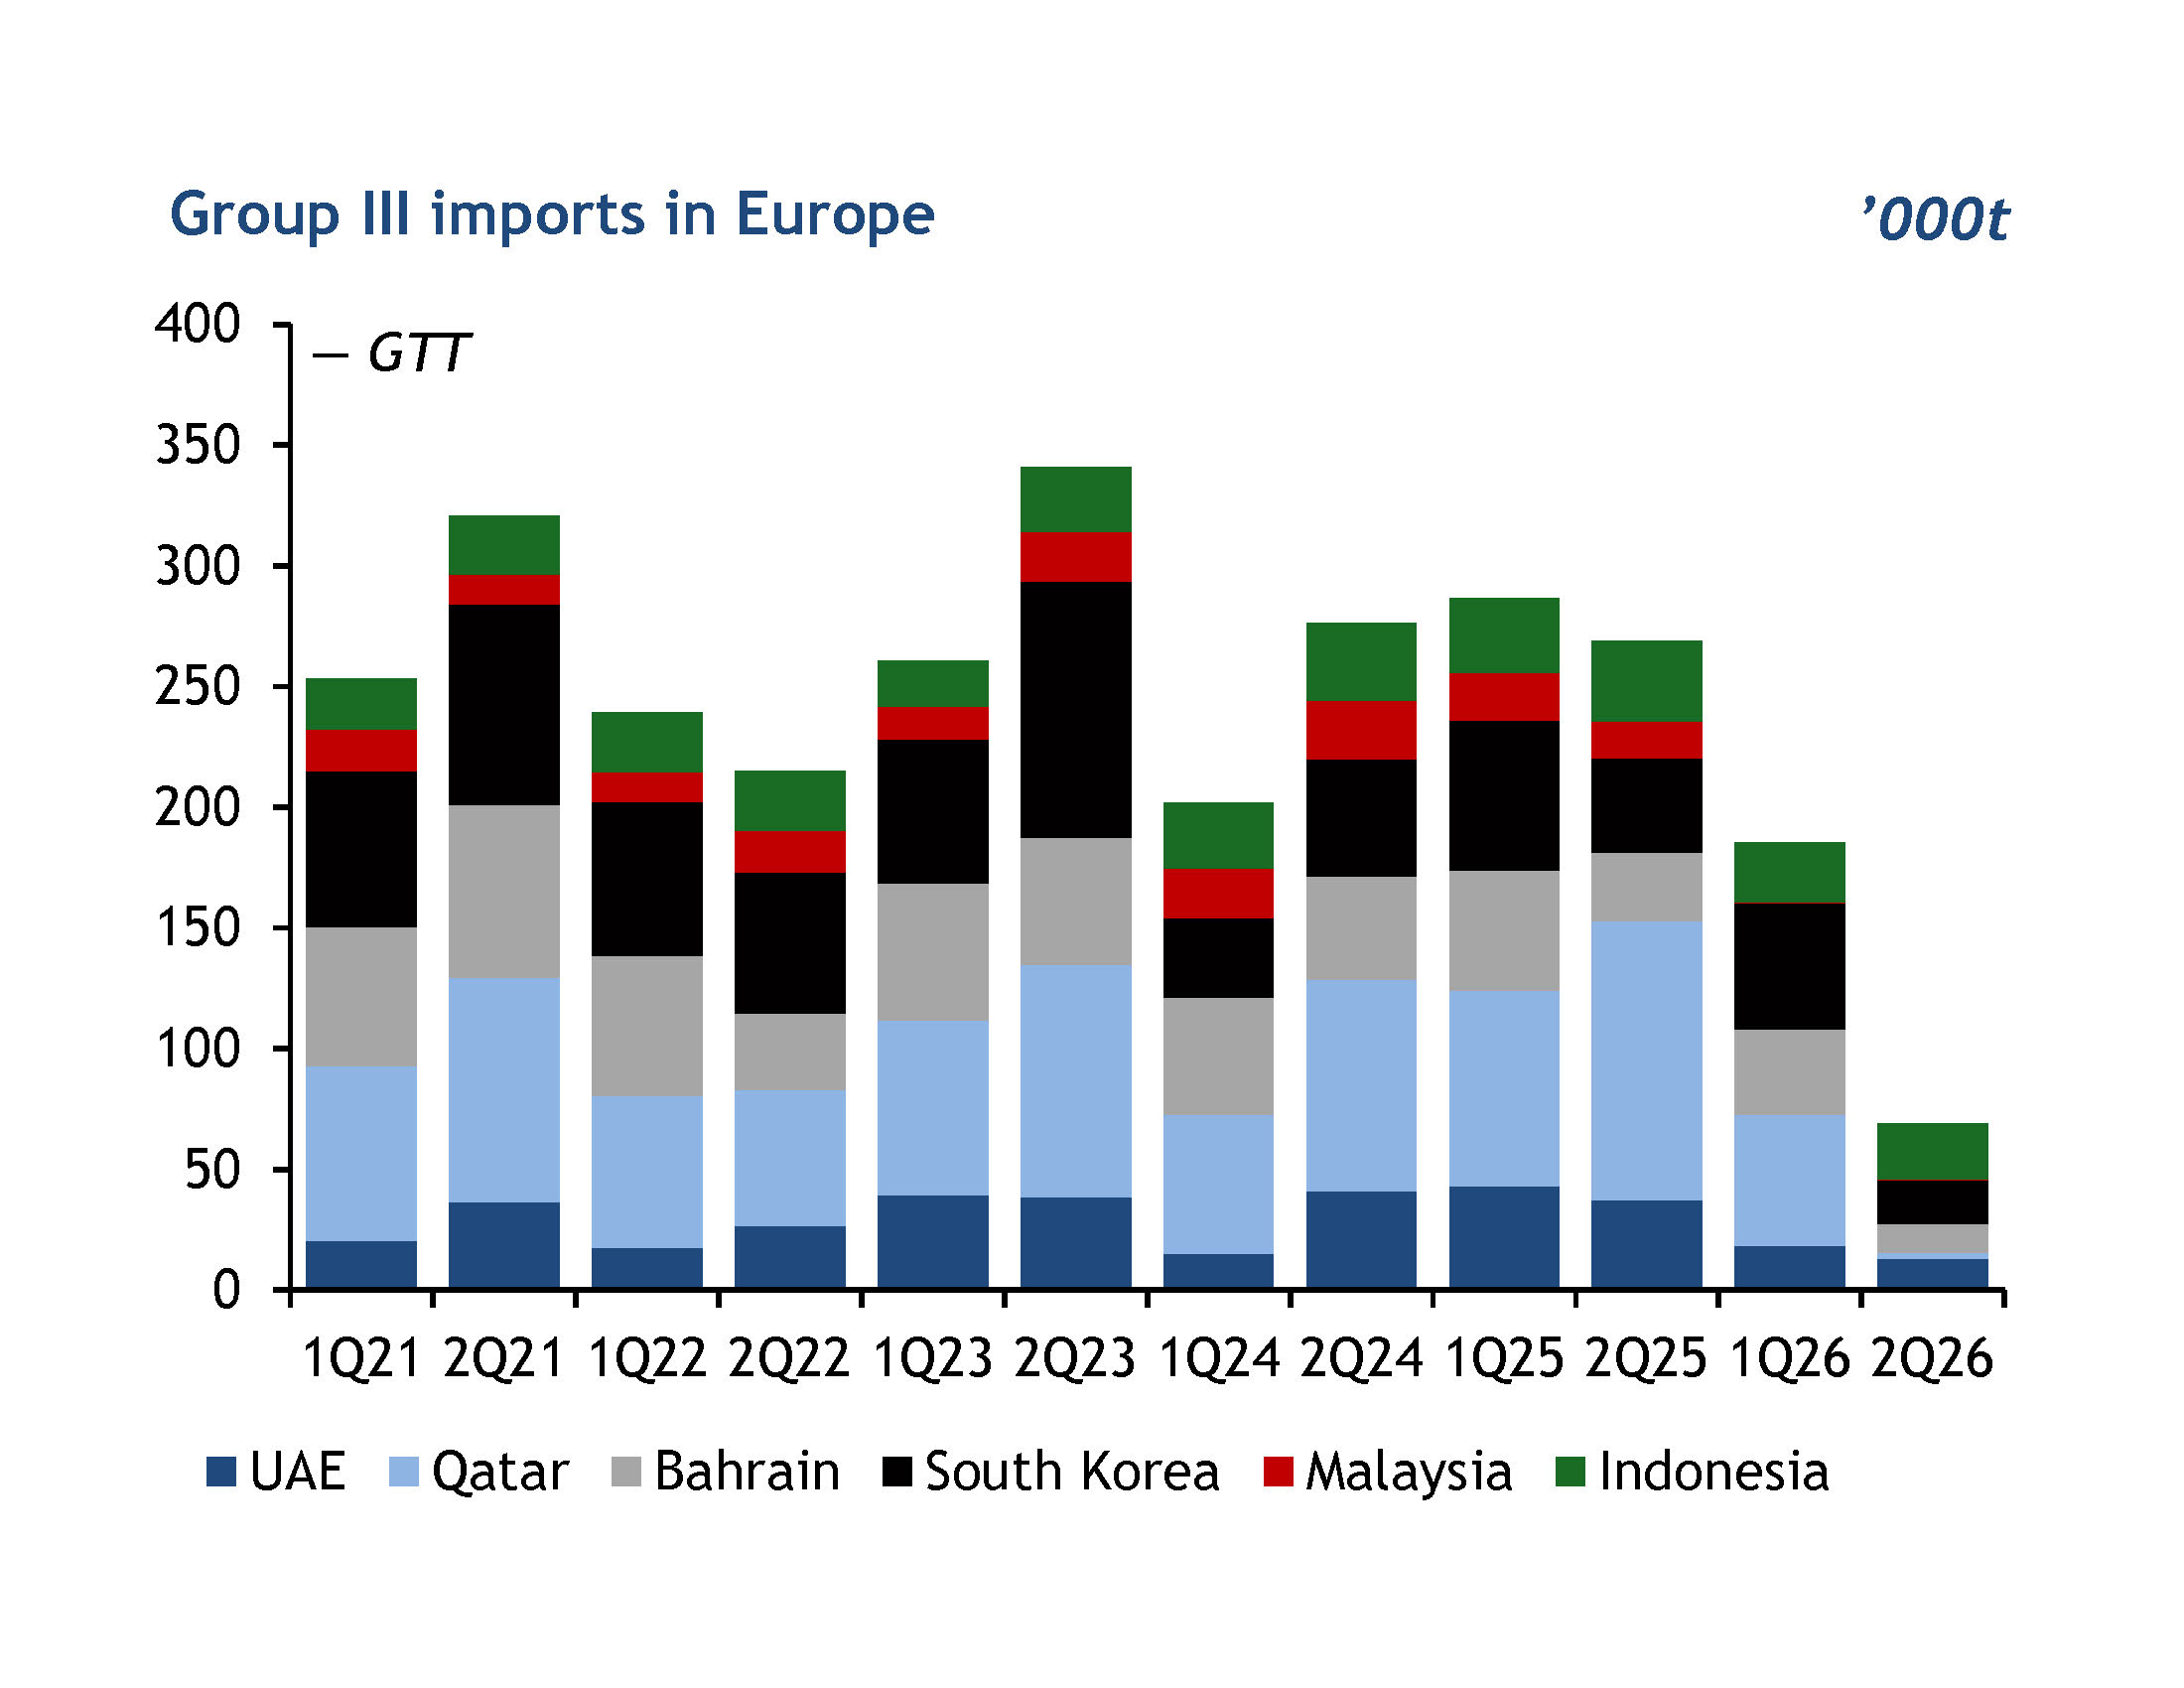
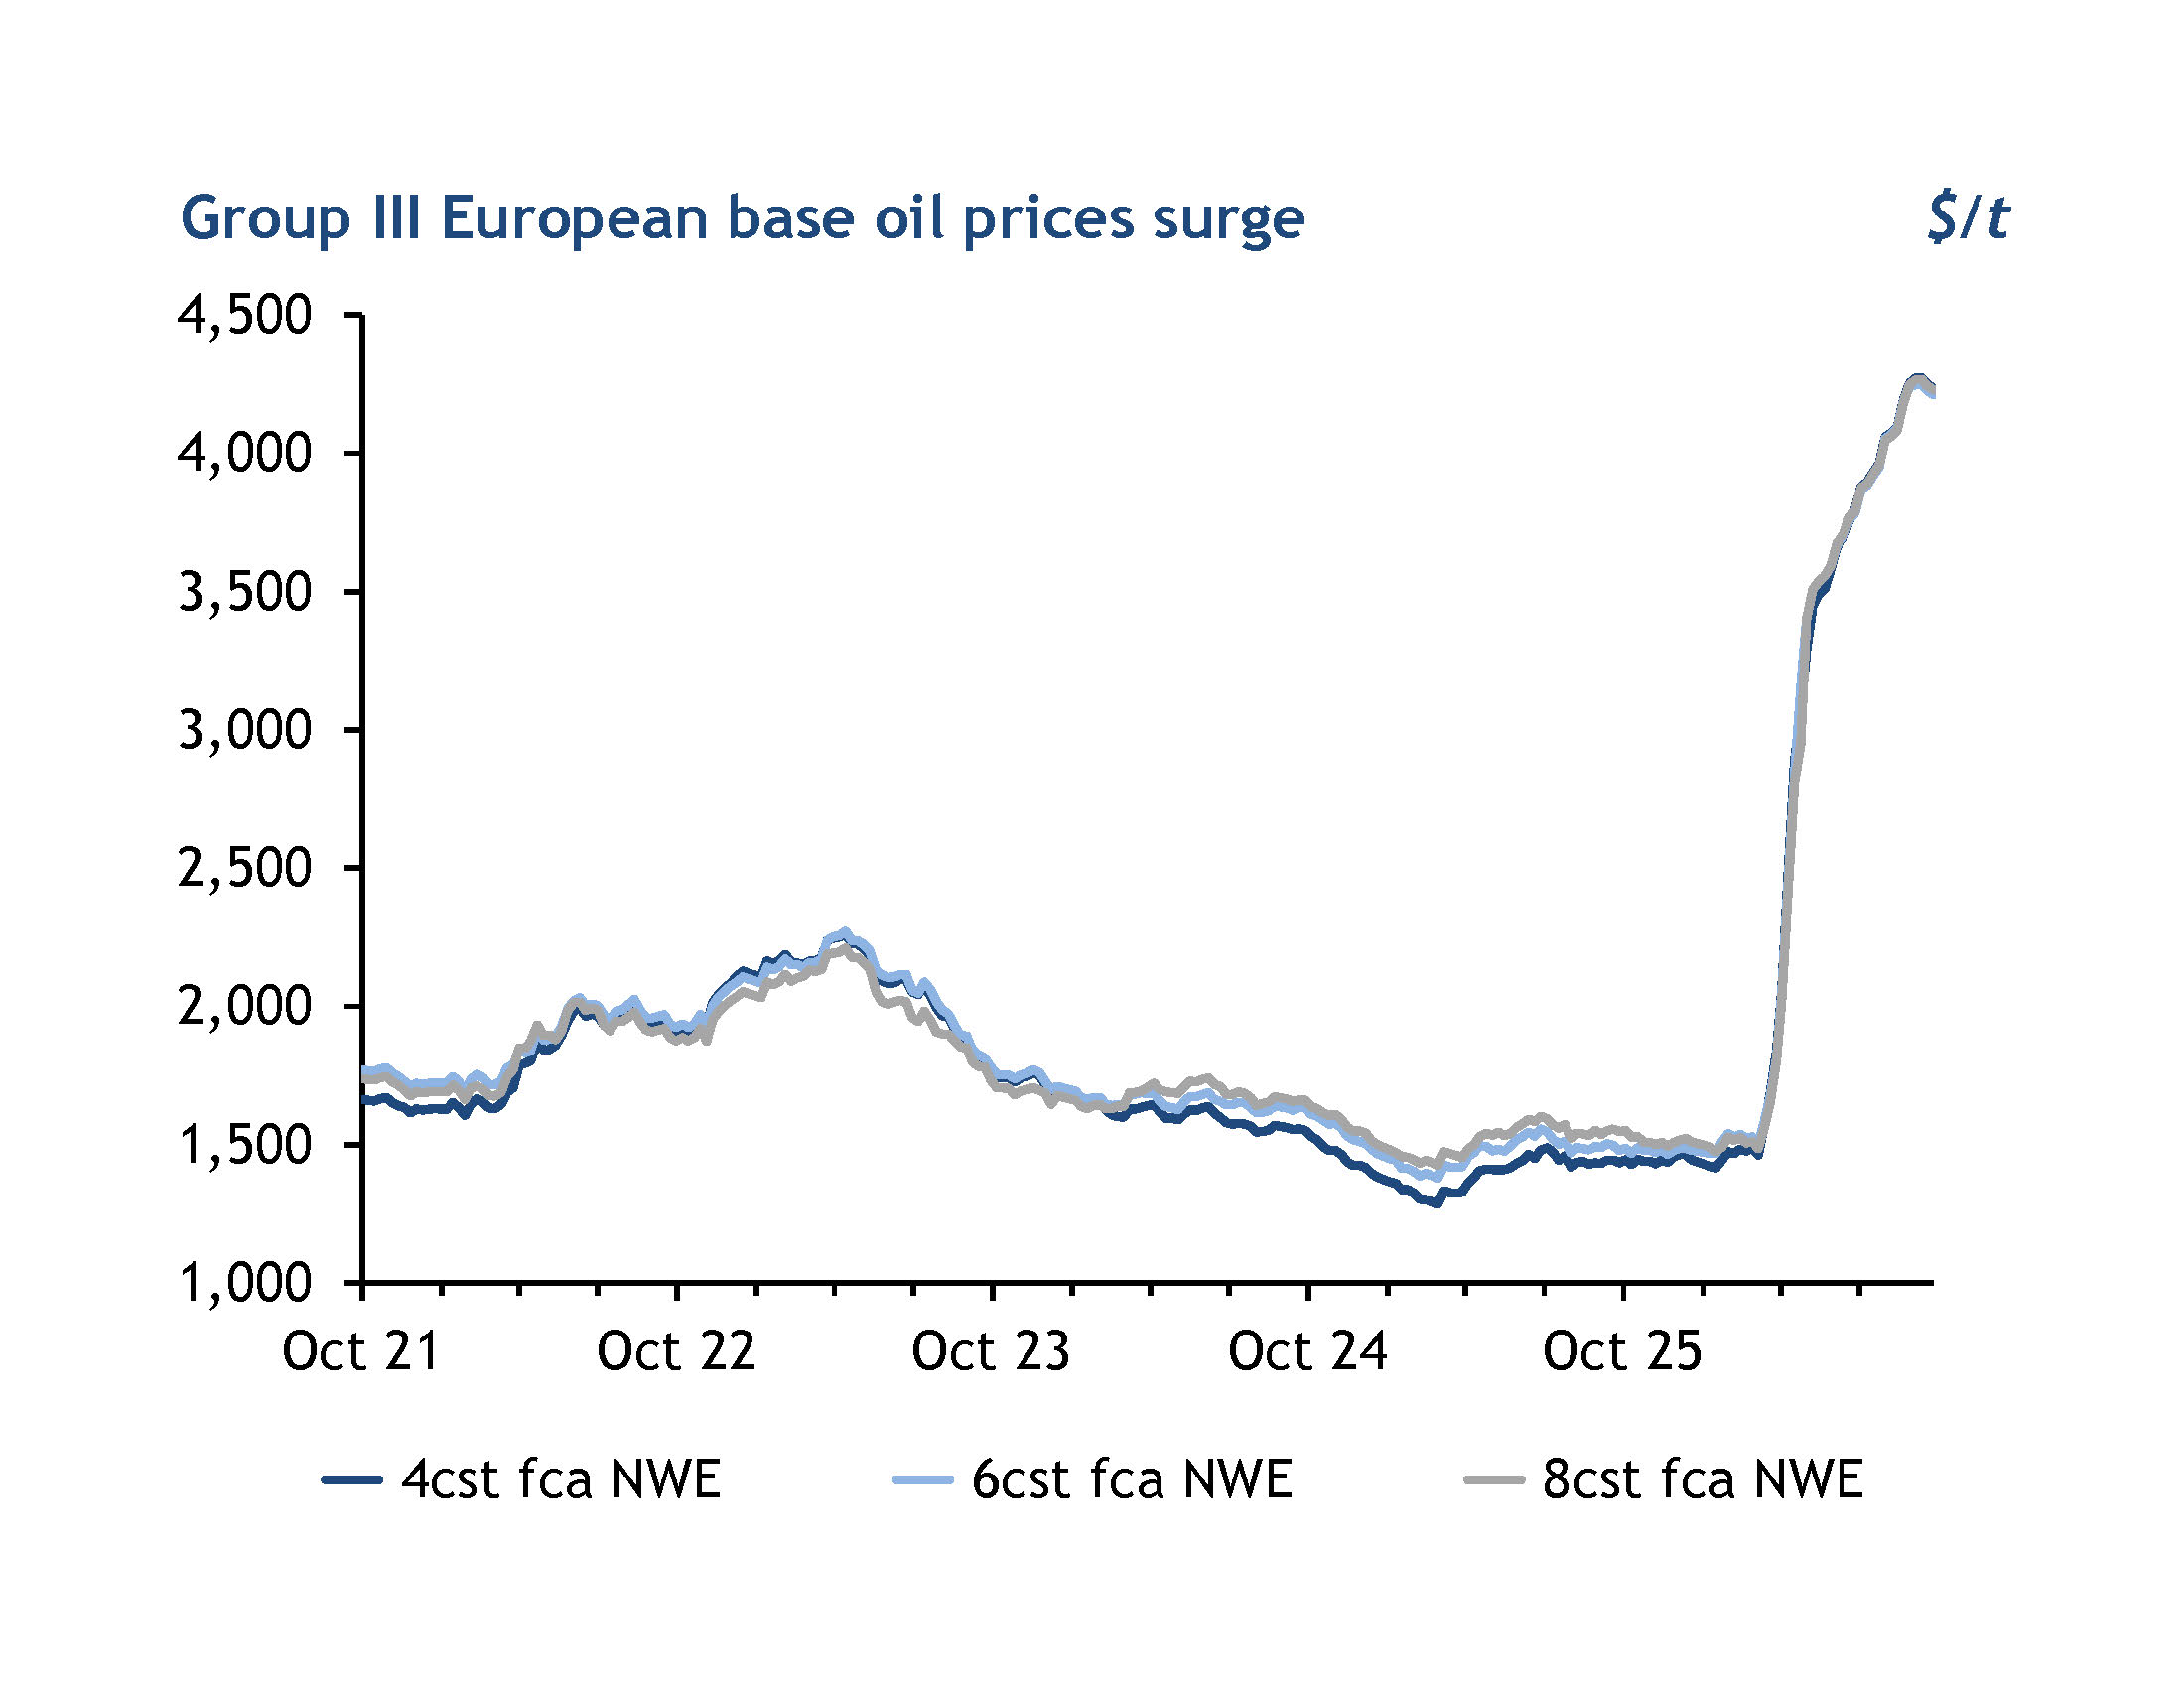
For now, the divergence between Group I and Group III markets remains stark. Weak demand and improving availability continue to weigh on Group I and II prices, while structural supply shortages keep Group III values firmly on an upward trajectory.
As supply chains continue to adapt to geopolitical disruptions, refinery maintenance cycles and shifting trade flows, market fundamentals remain highly fluid across all base oil groups. The contrasting trends seen in Group I, II and III markets highlight how quickly pricing dynamics can change as supply and demand conditions evolve.
In this environment, regular price assessments are essential for tracking market developments in real time, providing transparency into changing fundamentals and helping market participants respond confidently as pricing moves occur.
Argus provides that transparency with reliable, robust price assessments, published on time and accompanied by expert market commentary. Learn more about our coverage and the Argus Base Oils service here.
At a glance
- Group I and II prices declined amid weak seasonal demand.
- Supply disruptions failed to reverse the downward trend in Group I markets.
- Buyers remained well stocked after purchasing during earlier supply concerns.
- Group III supply stayed tight due to import disruptions and refinery maintenance.
- Record-high Group III prices persisted as buyers competed for limited volumes.


Never miss an episode
Stay ahead of change in the base oils market with expert insight from Argus. Receive the latest podcasts, analysis, blogs and market updates covering price movements, trade flows, supply trends and demand developments across Group I, II and III base oils
Sign up
