Steam cracker capacity addition: relief in sight
Global steam cracker operating rates have been trending downward from 89pc in 2018 to 79pc in 2023, driven by the combination of high-capacity increase and slower economic growth in recent years.
In Argus's latest Ethylene Analytics, a recovery is forecast to take place in the coming years as the recent wave of new capacity cools off, absorbing demand growth before the second wave of capacity addition outgrows demand from 2027-2029. This recovery is based on a modelled assumption of modest growth in the global economy and a slowdown in capacity expansion. Historically, olefins demand growth has trended in line with GDP growth on a global basis; in recent years this relationship has disconnected. This was a result of the imbalance between the service and manufacturing industries, but we anticipate the trend will revert sooner or later moving forward.
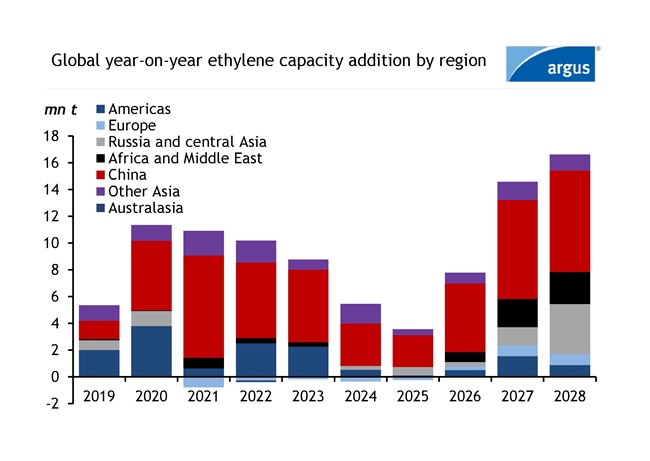
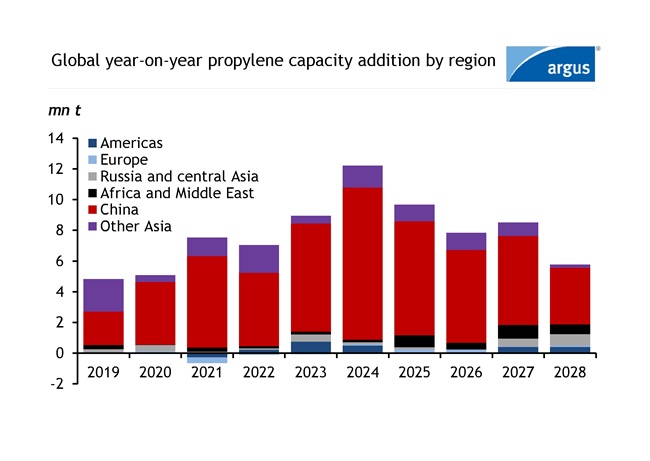
The petrochemical industry is experiencing high levels of upcoming capacity over the next five years. On a global level, ethylene and propylene capacity is expected to increase by 47.4mn t (4pc) and 44.0mn t (5pc), respectively, over the next five years while global capacity growth from 2018 to 2023 averaged at 4.5pc/yr for both ethylene and propylene. Most investment in ethylene production has gone into steam crackers where ethylene is the main product and propylene is produced as a co-product. Propylene will see a high-capacity increase from not only steam crackers but also from propane dehydrogenation (PDH) projects, which will delay the recovery of global propylene operating rates.
The first wave of ethylene capacity addition is cooling off, but a second wave is expected to kick off in 2026. However, propylene is currently undergoing its wave of capacity addition before seeing a slowdown from 2028 onward. On the propylene side of the olefins chain, 50pc of the upcoming capacity will come from PDH, 34pc from steam crackers and the rest will be a combination of sources from refinery, coal, and methanol.
Operating rates in all regions are being negatively impacted by the combination of high-capacity increase and slower global economic growth. Olefins demand has experienced slower growth over the past two years, with negative growth in 2022 as a result of high inflation and lower consumer spending.
Based on current market fundamentals there have been project delays across most regions and also rationalisation from uncompetitive units. With steam crackers running at lower-than-normal operating rates, rationalization of capacities is a significant unknown as what assets are to shut down are dependent on many factors such as company financials, politics, and integration factors. This makes the rationalization of specific units tough to predict.
As western nations are experiencing slower GDP growth, developing nations will be the key regions for olefins growth. We are seeing a slowdown in Chinese and northeast Asian GDP, but south Asian GDP has been holding strong. Polymer demand, which accounts for more than half of olefins consumption will be the main driver of olefins demand (65pc of ethylene gets consumed into PE and 71pc of propylene gets consumed into PP globally). From a supply perspective, 17pc (8mn t) of all upcoming cracker projects have yet to start construction, which will give operating rates a boost if delayed. Given the slowdown in global economic growth in the past two years, high interest rates, and inflation, the overall outlook is fairly bearish. Consumer spending, household disposable income, economic growth, project timelines, and rationalization from uncompetitive production facilities will be the main indicators of how quickly it will take for operating rates to recover.
Current announced projects
In the past five years, most steam cracker capacity increases took place in China and the trend is expected to persist over the next five years based on announced projects, but most regions are investing. Other Asian countries such as India, South Korea, Vietnam, and Indonesia are also investing. A total of 25.6mn t and 32.9mn t of ethylene and propylene capacity is expected to come online in China over the next five years. Below is the summary of upcoming stream cracker projects globally.
Chinese projects that are currently under construction include Wanhua Chemial, Yulongdao Refining & Petrochemical, Sinopec, Jilin Petrochemical and more. Joint venture steam cracker projects in China between domestic producers and multinational corporations have also started construction which includes Sabic-Fujian Petrochemical, Ineos Sinopec Tianjin, Shell CNOOC Petrochemical, BASF Zhanjiang, and ExxonMobil. These projects will increase ethylene capacity by 21.8mn t over the upcoming five years. Asian nations excluding China includes S-oil South Korea, Hindustan Petroleum India, Lotte Chemical Indonesia have also started construction which totals 5.2mn t of ethylene capacity.
Borouge, SATORP and a joint venture between CP Chem and Qatar Energy in the Middle East are also investing in new crackers with a total capacity addition of 5.2mn t. In Europe, Ineos Project One and PKN Orlen have announced projects while Sabic UK invested in a green project. The Sabic project involves restarting and converting its current cracker to run on hydrogen.
Russia has steam cracker projects slated to start up in the five-year span, including Nizhnekamskneftekhim, Irkutsk Oil, Baltic Chemical, and Amur GCC while Uzbekistan has also announced an expansion from Gas Chemical Complex. North America has three projects slated to come on over the next five years that will increase its capacity by 3.6mn t. North American projects include Shintech US, Joint venture CP Chem Qatar Energy, and Dow in Canada.
Argus’s Ethylene Analytics includes a global plant-level capacity dataset detailing expected project timelines.
Author: Dhanish Kalayarasu
Date: 15/05/2024


Spotlight content


Related news
USDA previews US-Mexico ethanol agreement
USDA previews US-Mexico ethanol agreement
Houston, 28 October (Argus) — The US Department of Agriculture (USDA) is in the final stages of talks with Mexico to boost ethanol exports, US agriculture secretary Brooke Rollins said on 26 October in Cedar Rapids, Iowa. Rollins declined to share details on what she described as a significant commitment from Mexico to increase its US ethanol purchases, but said the two sides had reached an initial agreement in concept after working with Mexico president Claudia Sheinbaum's administration. "As Mexico continues to integrate more ethanol into its energy mix, we saw that as a massive opportunity for our biofuels, ethanol and certainly… our corn farmers from the Midwest," Rollins said. Rollins estimated that a completed trade deal would deliver $1.5bn for the US ethanol industry and could increase ethanol exports by 32pc. Mexico began evaluating whether to incorporate ethanol as an oxygenate for its gasoline supply earlier this year after talks with US officials, but has not released details of a formal proposal. Mexico allows gasoline to have an ethanol content of up to 5.8pc in most of the country, but prohibits ethanol in Mexico City, Guadalajara and Monterrey, which instead require additive MTBE as an oxygenate under the Nom-016 rules to reduce tailpipe emissions. Mexico produces limited volumes of ethanol and relies primarily on imports to meet existing demand. The US exported less than 670,000 bl of ethanol suitable for fuel use to Mexico last year. The USDA rolled out the American Biofuel Trade Outlook in September , outlining four policy pillars aimed at increasing biofuel export markets, primarily for US ethanol. The plan includes addressing barriers to implementing gasoline fuel blends with up to 10pc ethanol in other countries, along with other priorities. Additionally the US and Mexico are also still in ongoing separate bilateral negotiations ahead of the USMCA free trade agreement review, after the collapse of US-Canada talks in August. President Donald Trump's administration has indicated that one of its priorities of any deal is to reduce the US' nearly $156bn trade deficit with Mexico toward zero. By Denise Cathey Send comments and request more information at feedback@argusmedia.com Copyright © 2026. Argus Media group . All rights reserved.
India's Adperma to start up phenol/acetone plant in Dec
India's Adperma to start up phenol/acetone plant in Dec
Singapore, 28 October (Argus) — Indian petrochemicals producer Adperma will begin commercial production at its new 345,000/215,000 t/yr phenol/acetone plant in Haldia, West Bengal from end-December 2026, the company told Argus on 28 October. Adperma is a subsidiary of Haldia Petrochemicals (HPL). The new plant is integrated with HPL's existing petrochemical complex, from which it will receive feedstock propylene and benzene. Adperma chief executive Sanjiv Vasudeva said earlier that India could begin exporting acetone after the plant comes on line, for a brief period before domestic demand matches capacity, although the focus remains on supplying the domestic market. The plant is expected to boost domestic phenol and acetone supplies and reduce its reliance on imports. Another Indian chemical producer, Deepak Nitrite, is establishing a production facility with a capacity of 300,000 t/yr of phenol, 185,000 t/yr of acetone and 100,000 t/yr of isopropyl alcohol. The project will support the group's expanding polycarbonate chain in Gujarat, where it already operates phenol-acetone assets and downstream polycarbonate facilities. India is a net importer of phenol, bringing in 284,488t in 2025 compared with exports of 23,097t in the same year, according to Global Trade Tracker (GTT) data. The country sources large volumes of phenol from southeast Asia and China, with Thailand and China making up around 32pc and 16pc, respectively, of India's phenol imports during 2021-25, GTT data show. India imported 149,877t of phenol from January-August this year, with Thai and China-origin phenol making up the bulk of the inflows at 65,155t and 31,530t respectively, according to GTT data. Indian petrochemical producers are increasingly exploring specialty chemical investments and seeking technology tie-ups with foreign companies to reduce reliance on imports. Asian phenol production margins have been poor because of high feedstock benzene prices and low consumption from the derivatives sector. The price spread between domestic Chinese phenol and benzene was at -Yn651.50/t on 15 October, falling from -Yn107.50/t on 17 September and Yn550/t on 13 August, Argus data show. By Sourasis Bose and Joonlei Lee Send comments and request more information at feedback@argusmedia.com Copyright © 2026. Argus Media group . All rights reserved.
Ethanol gaining favour as European bunker fuel
Ethanol gaining favour as European bunker fuel
London, 27 October (Argus) — Ethanol is gaining traction as a bunker fuel for methanol-fuelled vessels seeking to meet EU regulatory requirements, because ethanol-methanol blends can offer a lower-cost alternative to pure biomethanol. Ethanol can be used in methanol-fuelled engines with little or no modification. This has attracted interest from shipowners, because ethanol is cheaper than biomethanol and can be used in blends to reduce overall fuel cost. Companies including WinGD, Everllence and Wartsila have conducted successful tests using biomethanol and ethanol blends, as well as 100pc ethanol. In May, Rotterdam port completed its first ethanol-methanol blend bunkering operation. Barcelona port had its first 100pc-ethanol bunkering in July, carried out by Danish shipowner Maersk, which has undertaken its first 100pc ethanol voyage in the first quarter of the year. There are 161 methanol-fuelled ships operating, according to Norwegian classification agency DNV, which began including ethanol-fuelled vessels in its tracking in the first half of this year. The number of methanol-fuelled vessels is set to reach 448 by 2030, DNV said.Ethanol is cheaper and has a higher volumetric energy content than biomethanol. In September, average 75pc greenhouse gas (GHG) crop-based saving ethanol fob Amsterdam-Rotterdam-Antwerp (ARA) range was at an average €995/t, or €37/GJ. This is compared with more than €896/t or €56/GJ for biomethanol in the same period. The average value of conventional methanol was just over €434/t or €27/GJ in September. Ethanol's volumetric energy content is 26.6 GJ/t (21 GJ/m³), compared with methanol and biomethanol at 16 GJ/t (12.6 GJ/m³). The economics are further improved by the duty treatment of marine fuel. Ethanol imported to the EU for use as bunker fuel pays no duties, while material supplied for the European road-fuel market faces standard duties of €192/m³ for undenatured ethanol and €92/m³ for denatured ethanol, unless preferential trade arrangements apply. Blending ethanol with biomethanol can lower overall cost and increase energy density. Biomethanol provides the greenhouse gas (GHG) reduction required for FuelEU compliance, which first generation ethanol — produced from sugar, wheat or corn — cannot. FuelEU requires a 2pc reduction, rising to 6pc in 2030. Ethanol can also act as a substitute for marine gasoil (MGO) in emission control areas (ECAs) because of its low sulphur content. Blending trials involving biomethanol and very-low sulphur fuel oil (VLSFO) or marine gasoil (MGO) had faced technical challenges, specifically related to the flash point of the final product, participants said. Demand for marine ethanol could rise further in the coming years. In the Netherlands, a key bunkering market, waste-based ethanol and biomethanol made from feedstocks categorised under Annex IX Part A of the EU renewable energy directive would be eligible to generate Dutch marine ZRE tickets. This could incentivise marine fuel suppliers to keep marine waste-based ethanol and biomethanol prices competitive with non-ZRE eligible fuels, in order to generate enough ZREs to meet their annual obligations, and avoid securing expensive ZREs from over-compliant peers. It could also offer an alternative route to ZRE generation beyond advanced Fame biodiesel, the most common ZRE-eligible fuel currently bunkered in the Netherlands. Argus assessed ZREs at 21.75c/kgCO2e on Monday, 26 October. For one tonne of waste-based ethanol with 90pc GHG savings, this would roughly generate ZRE tickets worth $556/t. By Natália Coelho, Toby Shay, Madeleine Jenkins and Hussein Al-Khalisy Send comments and request more information at feedback@argusmedia.com Copyright © 2026. Argus Media group . All rights reserved.
Sabic expects petchem project delays in the Middle East
Sabic expects petchem project delays in the Middle East
Mumbai, 27 October (Argus) — Saudi petrochemical producer Sabic expects delays in the startup of new projects in the Middle East because of ongoing supply chain disruptions caused by the US-Iran conflict, it said on 26 October. "We expect delays in the new projects, especially in the Middle East, but no cancellation," Sabic chief financial officer Salah Al-Hareky said. Rapid petrochemical capacity expansions in China have intensified price competition this decade, and several producers have begun to rationalise their capacities or modify feedstock slates to grapple with oversupply and geopolitical uncertainty. The current upside in petrochemical prices would likely recede, according to Al-Hareky. "Is it six months, one year? We do not know, but it is temporary," he said. Sabic's Fujian complex in China remains on track for startup in the fourth quarter, it said. The firm also reported a 24pc increase in third-quarter petrochemicals sales volumes from the second quarter to 6.71mn t. Several key projects are scheduled to start operations in the Middle East in the coming years. The new capacity includes Borouge 4 in the UAE, which would add 1.4mn t/yr of production to the UAE-based producer's existing portfolio. Borouge would ramp up operations throughout the year after initial startup of production, it said in April. Satorp, a joint venture between Saudi state-controlled Aramco and TotalEnergies, would add another 1.7 mn t/yr of ethylene capacity in Saudi Arabia. Commercial operations at the project were expected to begin in 2027. Chevron Phillips Chemical and state-owned QatarEnergy are also investing in an ethylene cracker with a capacity of 2.08 mn t/yr. The project was initially expected to be completed by 2026. The companies did not immediately respond to Argus ' requests for comment on the startup dates. By Sourasis Bose Send comments and request more information at feedback@argusmedia.com Copyright © 2026. Argus Media group . All rights reserved.